Redfin featured ShopProp founder and managing broker Rob Luecke in its guide, How Much House Can I Afford With an FHA Loan? His advice: start with a monthly payment you can comfortably carry, account for the full cost of ownership, and keep money available after closing.
A low down payment can help make a purchase possible. It does not, by itself, tell you whether that home will be affordable to own.
Rob Luecke’s advice in Redfin
“When looking at an FHA loan, I’d start with a monthly payment you feel comfortable with,” says Rob Luecke of ShopProp. “Be sure to include taxes, homeowners insurance, FHA mortgage insurance and any HOA dues in that monthly number. Eligible buyers can put as little as 3.5% down, but you’ll still want to budget for closing costs and leave yourself a cushion for repairs and everyday expenses.”
Source: Redfin’s FHA affordability guide, “Cash you need at closing.” Rob is one of several real estate and lending contributors quoted in the article.
Work backward from a comfortable monthly payment
A lender’s preapproval is useful, but it is not a spending target. Before deciding on a home price, write down the housing payment that leaves room for your other commitments, savings, and unexpected expenses.
Then ask your lender to price the actual property, including:
- Mortgage principal and interest.
- Property taxes, using an estimate appropriate for your purchase rather than assuming the seller’s current tax bill will remain unchanged.
- Homeowners insurance and any additional coverage the property requires.
- FHA mortgage insurance.
- HOA or condominium dues, if applicable.
Keep utilities, routine maintenance, and a repair reserve in a separate ownership-cost estimate. They may not be part of the lender’s mortgage payment calculation, but they still come out of your money each month.
The Consumer Financial Protection Bureau’s Loan Estimate explainer shows where to find the projected payment, closing costs, and estimated cash to close. Compare written estimates from lenders using the same purchase assumptions.
3.5% down is not the same as total cash needed
For eligible FHA borrowers, the minimum down payment can be as low as 3.5%, as HUD explains. Qualification still depends on credit, income, debts, the property, and lender requirements.
On a hypothetical $350,000 purchase, 3.5% is $12,250. That calculation covers the down payment only—not all the money needed to complete the purchase.
Ask the lender for an itemized cash-to-close estimate that also accounts for lender and settlement charges, prepaid taxes and insurance, initial escrow deposits, and how upfront FHA mortgage insurance will be handled. Some costs may be financed or offset by permitted credits; do not assume that treatment until your lender confirms it. Keep your planned post-closing cushion separate.
Representation costs belong in the conversation, too
ShopProp provides full-service buyer representation with a managing broker on every team and transparent buyer fees starting at $1,995, with the applicable fee depending on the home’s price and your agreement. We have served buyers and sellers since 2007, across more than 4,000 transactions.
Where a buyer-agent commission is available and exceeds the agreed ShopProp fee, an eligible buyer rebate may reduce transaction costs. Commissions are negotiable, not guaranteed, and the amount and permitted use of any rebate depend on the agreement, applicable law, and lender approval.
For an FHA purchase, do not assume a commission rebate can fund the required down payment or arrive as unrestricted cash. Disclose any proposed rebate or credit to the lender early and have the lender and closing team confirm how it may be used and documented.
A documented closing—not an FHA loan example
ShopProp’s Top Results records include the following completed transaction. It illustrates why buyers should ask about representation costs. The public record does not identify its financing type, so we are not presenting it as an FHA purchase.
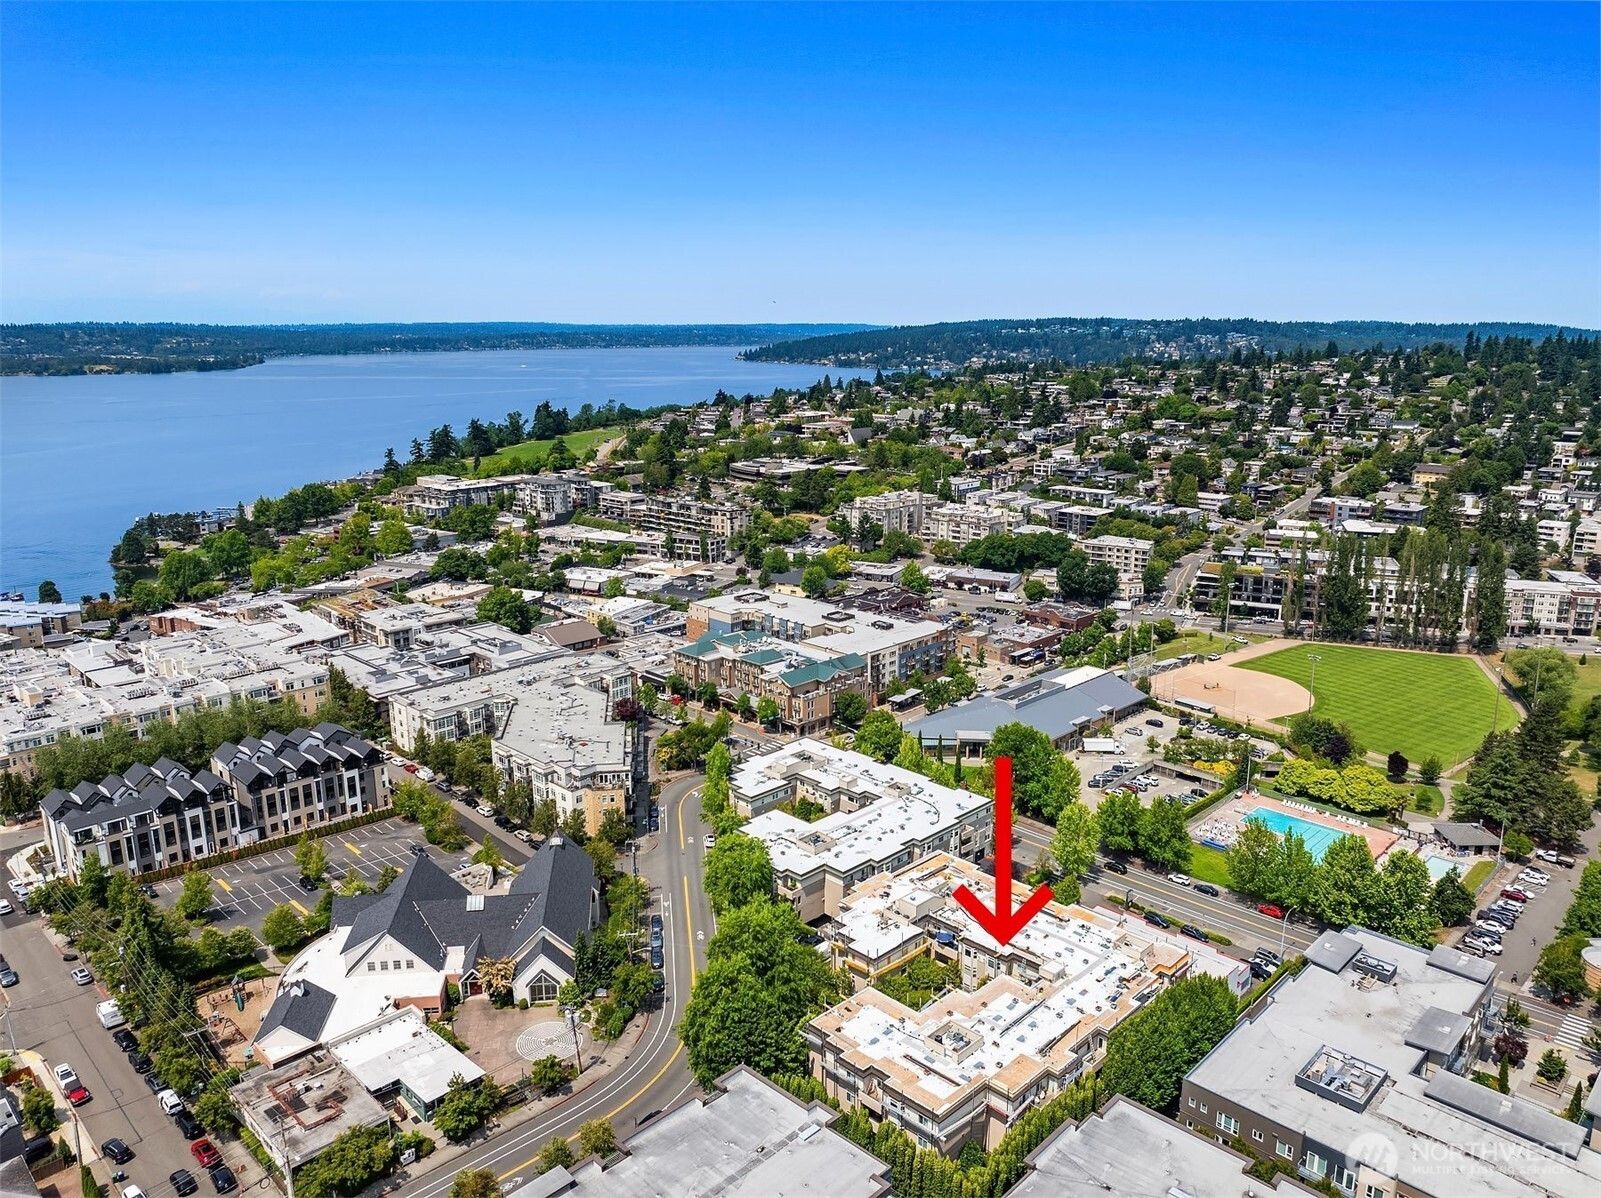 SOLD
- Closed: July 10, 2026.
- Purchase price: $400,000.
- Fee Paid: $2,995.
- Estimated rebate/savings reported in Top Results: $7,005.
The published comparison uses a $10,000 market-commission estimate: $10,000 − $2,995 = $7,005. This is a historical transaction record, not a current fee quote, guaranteed rebate, or claim that commissions have a standard rate.
Before you make an offer
- Choose your comfortable monthly housing total. Leave room for the rest of your life.
- Compare written financing estimates. Ask whether FHA or another available loan structure better fits your situation.
- Confirm cash to close and cash left afterward. Resolve any seller credit, buyer rebate, or mortgage-insurance questions before relying on those amounts.
Thank you to Redfin for including Rob’s perspective. Read the full Redfin article for its FHA affordability discussion and additional expert advice.
Calculate your potential representation savings · Get started with ShopProp · Chat with our AI assistant
ShopProp’s calculator estimates representation savings; it is not a mortgage qualification tool. This article is general education, not a loan offer or an approval determination. Confirm current FHA requirements and your options with an FHA-approved lender.
ShopProp in the Press
Explore reporting, company announcements, and public discussion about ShopProp:
- NPR: Flat-fee brokers offer an alternative
- MarketWatch: Changes to buying a home after the NAR settlement
- New York Post: What buyers should know about commission changes
- Business Wire: ShopProp’s July 2024 company announcement
- Orange County Register: Home buying a la carte
- Viral on X: Sheel Mohnot’s post about an Atherton purchase